Fort Collins vs. Denver vs. Colorado Springs: Which Market Is Winning Right Now?
Two hundred thirty-eight Fort Collins sellers changed their price in September. At the same time, Fort Collins held its value better than Denver or Colorado Springs over the last five years. Both of those things can be true at the same time, and once you see why, you'll know exactly how to play this winter.
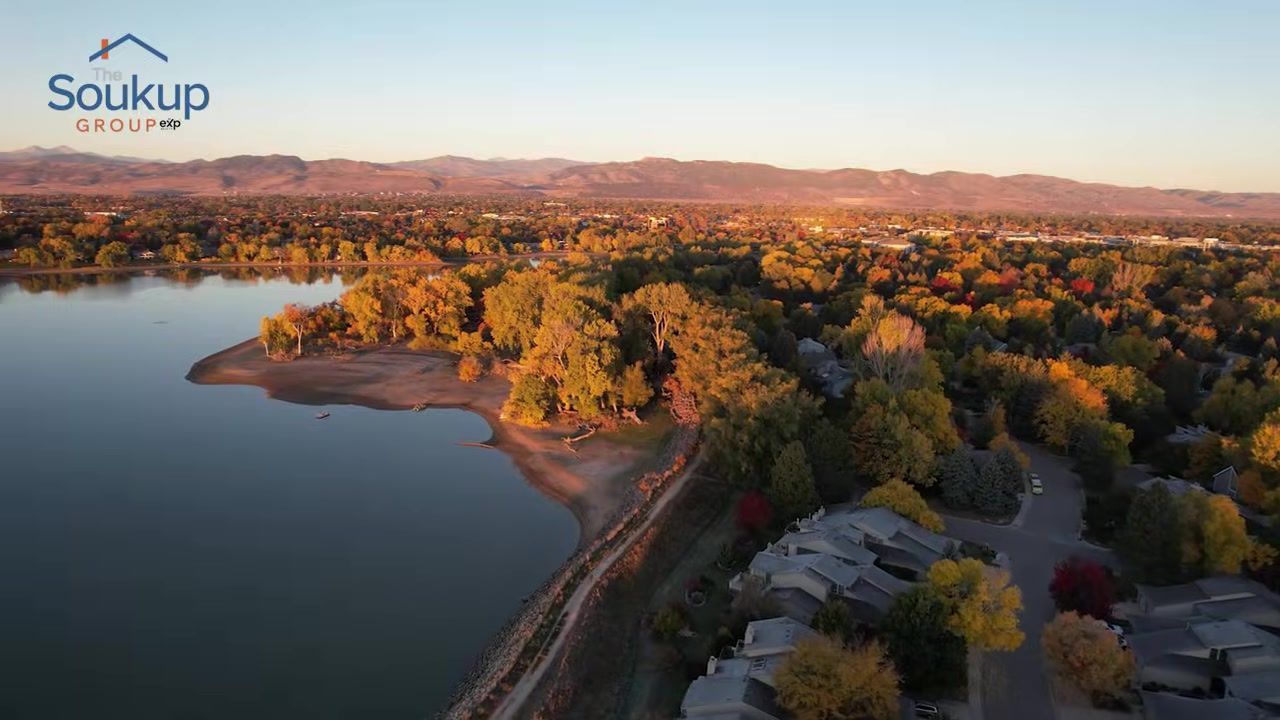
Every month I look at Fort Collins pretty much in a vacuum. This month I wanted to zoom out a little bit. How does Fort Collins stack up against the two other big dogs on the Front Range? We're looking at September 2026 side by side by side: who held value, who's moving inventory, and what sellers are actually giving up at the closing table. Then we'll dig into Fort Collins up close, how fast new listings got picked up, how many sellers had price reductions, what concessions buyers are getting, and a forecast for October through December.
If you're thinking about selling in the next six months, don't guess at your price in this market. Give my team and I a call, text, or email. We'll put together a pricing breakdown for your specific home and situation, what's sold near you, what's sitting, what concessions buyers are getting, so you can have the full picture. And if you're buying, we'll send you the September price drops in the zip code you're targeting. Whether you're three months out or three years out, we would love to be an asset on your team.
Table of Contents
Fort Collins: Strong Value Retention Despite Price Cuts
Fort Collins closed 118 sales in September, down 15.7% from last year. That sounds rough until you realize Denver and Colorado Springs both saw similar drops, 12.3% and 18.6% respectively. This isn't a Fort Collins problem. It's a Front Range thing. Fewer sales everywhere, but the story behind the numbers is what matters if you're buying or selling right now.
The median sales price landed at $604,950, down 3.2% from last September. But here's where it gets interesting: price per square foot actually climbed to $265, up 6% year-over-year. That tells you smaller homes sold in September, not that homes got cheaper. That's why we always watch price per square foot instead of just the headline median. The rolling 12-month price per square foot has been flat for about a year, and I expect flat into year end with normal month-to-month noise. I'm not calling for a drop and I'm not calling for any jump.
Fort Collins had 493 homes for sale at the end of September, up 14.1% from last year. That sounds like a lot of inventory growth until you remember September 2010, when the Iris MLS Fort Collins area report showed about 1,390 active detached listings. We're nowhere near that. This is more of a normalizing market, not a 2010 market. Months of supply sits at 3.3, which is still below the balanced market threshold of 4 to 6 months. That means it still favors sellers, even with the uptick in inventory.
Here's the thing: Fort Collins inventory is up even though fewer people listed. New listings dropped 14.6% to just 199 in September, while Denver and Colorado Springs both saw new listings climb. Fort Collins inventory is coming from homes that are sitting, not a new wave of sellers. The median days on market hit 48 days, and homes that went under contract in the first two to three weeks sold at 100% of list. Homes that sat 60 days or more sold at about 98.5% and paid higher concessions.
Two hundred thirty-eight Fort Collins detached listings changed price in September. Compare that to the 493 homes for sale at month end, roughly one listing for every two on the market. The median time on market for those listings was 67 days. The biggest group, 82 homes, was at 31 to 60 days when they made the price reduction. That's the first price cut window: a month or two in with no offers, and the sellers are beginning to blink. Thirty-one of the 238 were builder listings. Builders are adjusting too.
A price cut is not necessarily a failure. Most of those homes priced off of what the spring market was bringing in. The fall market is a different animal. The sellers who adjust early sell the fastest, and the ones who chase the market down end up expired, waiting, multiple price reductions. Of the 238 homes that changed price, 40 went under contract or sold, 167 were still active, and 31 expired or withdrawn. If you're planning to list this winter or next spring and you want to price it right the first time, give me a text or call and we'll set up a plan for success.
Now let's talk about what sellers actually gave up. One hundred fifteen Fort Collins detached homes closed in September. The median sales price was $599,990 against a median list price of $610,000. The median home sold at 100% of its list price. Thirty-nine sold right at list, 22 over, and 54 under. For the ones that sold under, the typical gap was about $13,950. But remember, this is against the final list price. Many of those homes had a price reduction and then sold at 100% of list after that cut.
Here's what really matters: 63 of those 115 homes, 55%, had some sort of seller concession at closing. The median concession was $8,660, roughly 1.2% of the price. Most land between $5,000 and $10,000. Homes that sat for 60 or more days? Sixty percent gave concessions with a median of $10,000. Homes picked up in the first two to three weeks? One in three gave a concession, but the median was only $2,000. Put it together: sellers netted about 97.9% of list price against all September sales. Sellers are holding the price and paying the buyer's closing costs or rate buydown instead. The headline looks strong, but the checks are coming at the closing table to the buyers.
Speed matters. Of the 202 detached homes that hit the market in Fort Collins in September, 61 of them, 30%, were under contract or sold by October 9th. The median was 24 days. Only 11 went under contract inside of two weeks. Most took 15 to 30 days. Your first two to three weekends are your most important weekends when it comes to pricing, marketing, and what your home's actually going to sell for. The listed Thursday, multiple offers by Sunday days are mostly gone. A well-priced home is getting picked up anywhere between one to three weeks.
Here's something that might surprise you based on price bands. Homes under $500,000: 6 of 39 went under contract. $500,000 to $700,000: 30 of 94. $700,000 to $1 million: 21 of 45, nearly half. And $1 million plus: only 4 of 24. That $700,000 to $1 million price band moved the best last month. Move-up buyers with equity are still out there and are able to parlay equity, rate buydowns, seller concessions. They're leveraging the market as it currently sits.
Fort Collins has hard boundaries: Wellington to the north, Loveland to the south, Timnath and Windsor to the east, and the foothills to the west. There's limited land to develop. Policy has made it harder for developers to put up homes fast enough. Overall it's a market that seems to have more demand than supply almost at all times, at least in the last 10 to 15 years. That's why Fort Collins always seems to be a strong, resilient market holding value.
Denver: Three Years of Sliding Prices
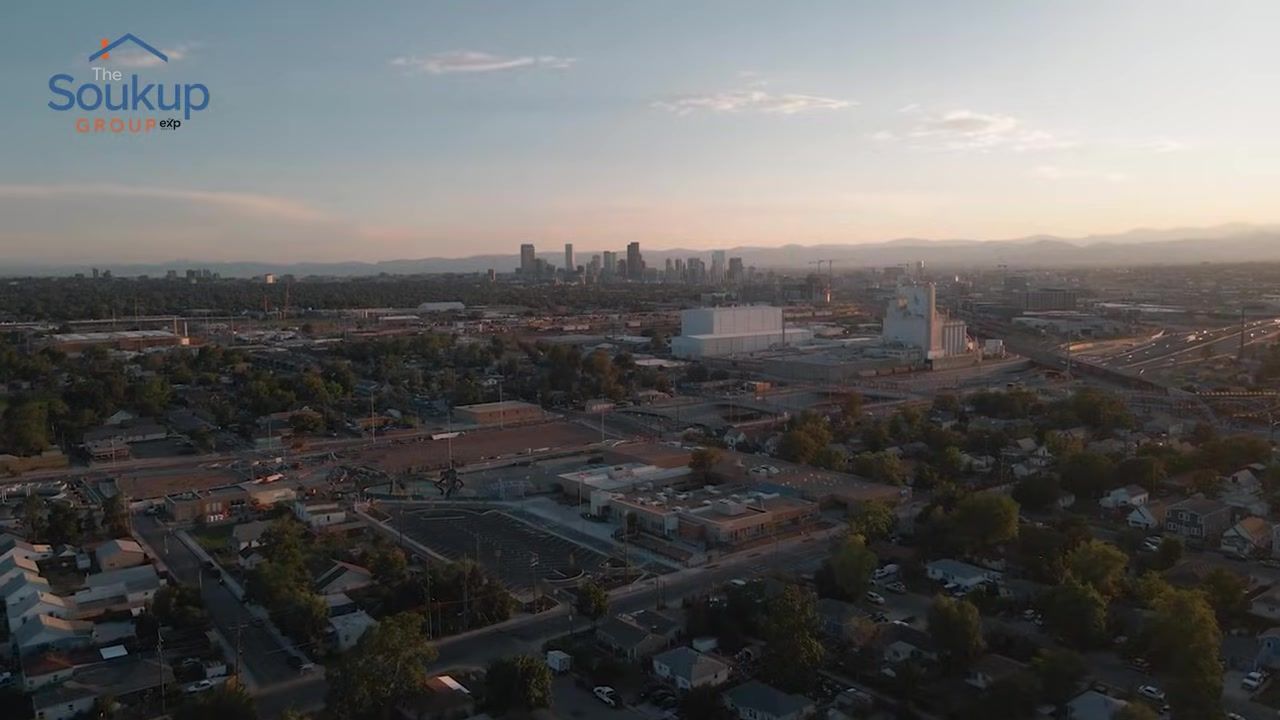
Denver closed 456 sales in September, down 12.3% from last year. Homes under contract dropped just 0.8% to 468, which is a much smaller slowdown than Fort Collins or Colorado Springs. New listings climbed 14.2% to 846, and inventory jumped 14.7% to 1,799 homes for sale. Denver sellers came onto the market while Fort Collins sellers pulled back.
The median sales price hit $615,000, down 2% from last September. Price per square foot landed at $326, down 1.5% year-over-year. That's the only one of the three markets where price per square foot actually dropped. Months of supply sits at 3.5, still below balanced market territory but climbing every summer. The median days on market was 22, though Denver's MLS counts that until they get an offer, not until close, so it's not quite apples to apples with Fort Collins.
Here's the big picture: Denver has been sliding for almost three years. Since December 2021, Denver is up just 4.2%, the weakest of the three cities. Off its own peak, Denver is down 5.7%. Over the last 12 months versus the 12 months before, Denver is down 1.3%. That's a market that's been giving back value while Fort Collins and Colorado Springs held on better.
My forecast for December puts Denver at about 2.1 months of supply. That's still tight, still favoring sellers, but the pattern is clear: every summer the peak is a little bit higher than the last. Denver is normalizing, not crashing, but it's not holding value the way Fort Collins is.
Colorado Springs: Touching Balanced Market Territory
Colorado Springs closed 188 sales in September, down 18.6% from last year, the steepest drop of the three. Homes under contract fell 6.9% to 176. New listings climbed 6.6% to 291, and inventory jumped 19.7% to 855 homes for sale. That's the highest inventory growth of the three markets.
The median sales price landed at $491,047, up 3.4% year-over-year. That's the only market where the median price actually climbed. But price per square foot tells a different story: $209, down 2.8% year-over-year. Again, smaller homes sold, which pushed the median up even as the price per square foot dropped. Months of supply hit 4.0, just touching the balanced market threshold. The median days on market was 35.
Since December 2021, Colorado Springs is up 9.2%. Off its own peak, the Springs is down just 0.9%, the best of the three at holding value from the peak. Over the last 12 months, the Springs is down 0.7%, basically flat. My forecast for December puts the Springs at about 3.0 months of supply, the loosest of the three markets but still not a buyer's market by any stretch.
Colorado Springs is normalizing faster than Fort Collins or Denver. More inventory, more months of supply, and it's the only market that's truly touching balanced territory. But it held value better from its peak than Denver did, and it's still climbing year-over-year on the median price even as the price per square foot softens.
Which Front Range Market Is Right for You?
All three markets are down in closed sales year-over-year. Fewer sales is a Front Range trend, not a Fort Collins-specific problem. But the way each market is handling the slowdown tells you a lot about where to put your money and how to negotiate if you're buying or selling right now.
Choose Fort Collins if you want the market that held value best over the last five years. Fort Collins is up 18% since December 2021 versus Denver's 4.2% and Colorado Springs' 9.2%. Fort Collins gave back the least from its peak, down just 2.7% versus Denver down 5.7% and the Springs down 0.9%. Fort Collins has hard development boundaries and policy constraints that limit supply growth. There's not a ton of land to develop, and more demand than supply for the last 10 to 15 years. The trade-off: Fort Collins is the tightest market heading into winter. My forecast puts Fort Collins at 1.8 months of supply by December, the lowest of the three. You'll have the least inventory to choose from, but you're buying into the market that punches way above its weight on holding value.
Choose Denver if you want the most inventory and the loosest pricing. Denver has been sliding for almost three years. It's given back the most value from its peak, and it's the only market where price per square foot actually dropped year-over-year. But Denver had more new listings in September while Fort Collins pulled back, and it has the most homes for sale of the three. My forecast puts Denver at 2.1 months of supply by December. You'll have more choice than Fort Collins, and sellers are adjusting. The trade-off: Denver hasn't held value the way Fort Collins or the Springs have. If you're betting on a rebound, you're betting on a market that's been softening for three years.
Choose Colorado Springs if you want the most balanced market and the best peak-to-now value retention. The Springs is the only market that's truly touching balanced territory at 4.0 months of supply. It held value best from its peak, down just 0.9%, and the median price is still climbing year-over-year even as the price per square foot softens. My forecast puts the Springs at 3.0 months of supply by December, the loosest of the three. You'll have the most negotiating room and the most inventory to choose from. The trade-off: the Springs had the steepest drop in closed sales, and inventory is climbing faster than Fort Collins or Denver. It's normalizing the fastest.
All three markets are climbing in months of supply, but Fort Collins and Denver are still below balanced market territory. The Springs is just touching it. Fort Collins is the tightest, Denver is in the middle, and the Springs is the loosest. Fort Collins held value best over five years. The Springs held value best from peak to now. Denver gave back the most. If you want this scorecard specifically for your neighborhood, not the whole city, shoot me a text and your email and I'll make sure to get that for you.
What the Winter Forecast Means for Buyers and Sellers
Here's how I built the forecast. I take Fort Collins, how it moved from September to October, November, and December in each of the last three years. I use the middle of those and apply it to this September. It's a seasonal pattern, not a crystal ball. But it's a pattern that's held for years, and it tells you what to expect if you're planning to buy or sell this winter.
Homes for sale: 460 in October, 390 in November, 285 in December. Months of supply: 3.2 in October, 2.6 in November, 1.8 in December. New listings: 200 in October, 105 in November, 75 in December. Those holiday months truly bring down activity in this Northern Colorado market and really markets across the United States. Homes under contract: 120 in October, 105 in November, 85 in December. Closed sales: 130 in October, 105 in November, 120 in December. We think that final October-November market based on pending under contract is actually going to be a little bit higher than November.
Median days on market: 48 in September, 53 in October, 60 in December. Inventory drops off every winter. New listings fall off a cliff after October. December could land anywhere from about 265 to 325 homes, but watch the floor. December inventory went from 212 in 2023 to 209 in 2024, then pumped up to 233 in 2025. This year, probably around 285 based on where inventory levels are currently at, roughly 20% more choice than last winter.
For buyers, winter's a great window. I bought my house in December of 2016. We went under contract in November. Very opportunistic. There are going to be fewer buyers out and sellers who still need to move. Fifty-five percent of sellers are already paying concessions. The homes that have sat for 60-plus days are where the negotiating room is. That's where concessions ran the median of $10,000. Use the seller's motivation on your payment, not just the price. The buydown example we can talk about with you is a 2-1 or a permanent and what makes more sense for your situation.
I wouldn't wait for a 2010-style market. Fort Collins has held better value than Denver or the Springs. Flat is not falling, but it is a good time and some of the most leverage we've seen buyers have in the last 15 years. We're talking to a few clients right now on the buy side, investments, personal purchases, kiddie condos for families looking at places for their kids, and we're telling them, hey, be patient, be opportunistic. Look at the homes on the market. Look at the homes doing price reductions. We can plan between the first price reduction and day 60, 75, before that second price reduction. This is a great time to strike, especially if it checks off your boxes.
The better conversation right now is can you afford the monthly payment? Are there ways to get it with a 2-1 buydown or a permanent buydown? What are your thoughts on interest rates over the next 12 to 24 months? My biggest suggestion is plan that interest rates are not going down ever. Can you afford it today? Does it make sense? The Murphy Whitlock Group, who we do a ton of deals with on the lending side, are really pushing rate buydowns, 2-1s. The hope is that in a couple of years we see interest rates start to recede just a little bit. The MBA purchase applications are running about 5% behind last year in late August. Negotiate the payment, not just the price, especially if you're financing with 5%, 10%, 15%, 20% down. The sellers are getting their number, but the buyer is going to get a lower payment.
For sellers, there are going to be fewer competing listings in November and December. But also fewer buyers, and they're only going to be the serious ones. You're going to want to price it right on day one. Well-priced homes are going to go under contract in about 24 days, two to three weeks. The ones that miss pricing it right from the jump are going to be one of those 238 homes that saw price reductions. You're going to want to budget for a concession. More than half of September sellers paid one. Plan for it upfront instead of getting surprised at inspection or at the closing table or when the offer first comes in. Plan for a buyer requesting a concession.
If you can wait till spring, new listings are going to jump in March, more buyers come out. But of course, there's going to be more competition in the seller's market. And who knows where interest rates are? I don't necessarily suggest waiting and trying to time the market. Our team is super active and we've gotten a lot of good negotiating opportunities, but be aware you're also going to see those homes that are priced right, turnkey ready in a great neighborhood that are going to see multiple offers. You have to be aware of the market and that's really what we do. We're going to close about 85 to 90 deals this year, probably going to set a record for our team. All that means is that we're very active in this market and activity is what matters so that we can guide our clients the best way that we know how.
If you want to know what your home would sell for this winter, or if you want a list of homes that had a price drop in September in the zip code you're looking at, give my team and I a call, text, or email. Whether you're three months out or three years out, it'd be an honor to be an asset on your team.
Conclusion
Fewer sales everywhere on the Front Range, more homes to choose from, and sellers are paying concessions. Fort Collins has held its value better than the Denver or Colorado Springs market, and that hasn't changed. Fort Collins is up 18% since December 2021, gave back just 2.7% from its peak, and is heading into winter with the tightest inventory of the three markets. Denver has been sliding for almost three years, gave back 5.7% from its peak, and is up just 4.2% since December 2021. Colorado Springs held value best from its peak, down just 0.9%, and is the only market touching balanced territory at 4.0 months of supply.
The buyer play right now is a rate buydown versus lowballing. Fifty-five percent of September sellers paid concessions. The median was $8,660, and homes that sat 60-plus days paid a median of $10,000. Winter is an opportunistic buying window: fewer competing listings, fewer buyers, but serious buyers only. Well-priced homes go under contract in about 24 days. Spring brings more listings and more competition. If you're selling, price it right on day one and budget for a concession. If you're buying, be patient, be opportunistic, and negotiate the payment, not just the price.
Reach out to my team and I. We'd love to talk to you about your specific situation, whether you're three months out or three years out. Call/text me at 970-893-3533 or book a FREE consultation here and let's put together a plan that makes sense for your timeline and your goals.
FAQ
How much inventory will Fort Collins have by December 2026?
My forecast puts Fort Collins at about 285 homes for sale by December, down from 493 in September. That's roughly 20% more choice than last winter, when December inventory was 233 homes. New listings fall off a cliff after October, so most of December's inventory will be homes that have been sitting since fall.
Are sellers in Fort Collins paying concessions right now?
Yes. Fifty-five percent of September sellers paid some sort of concession at closing. The median concession was $8,660, roughly 1.2% of the price. Homes that sat for 60 or more days paid a median of $10,000. Homes picked up in the first two to three weeks paid a median of just $2,000. Sellers are holding the price and paying the buyer's closing costs or rate buydown instead.
Which Front Range market held value best over the last five years?
Fort Collins held value best over the last five years. Fort Collins is up 18% since December 2021, compared to Denver up 4.2% and Colorado Springs up 9.2%. Fort Collins gave back just 2.7% from its peak, while Denver gave back 5.7% and the Springs gave back 0.9%. Fort Collins punches way above its weight on holding value due to hard development boundaries and limited land supply.
What price range is moving fastest in Fort Collins right now?
The $700,000 to $1 million price band moved best in September. Twenty-one of 45 homes in that range went under contract, nearly half. Homes under $500,000 and over $1 million moved slowest. Move-up buyers with equity are still out there and are able to parlay equity, rate buydowns, and seller concessions. They're leveraging the market as it currently sits.
Should I wait for interest rates to drop before buying in Fort Collins?
Plan that interest rates are not going down ever. Can you afford it today? Does it make sense? Winter is an opportunistic buying window with fewer competing listings and fewer buyers, but serious buyers only. Negotiate the payment via rate buydowns (2-1 buydowns or permanent buydowns), not just the price. Fifty-five percent of September sellers paid concessions, and homes that sat 60-plus days paid a median of $10,000. This is some of the most leverage buyers have had in the last 15 years.
How long are homes sitting on the market in Fort Collins?
The median days on market in September was 48 days. Homes that went under contract in the first two to three weeks sold at 100% of list. Homes that sat 60 days or more sold at about 98.5% and paid higher concessions. My forecast puts median days on market at 53 in October and 60 in December. Your first two to three weekends are your most important weekends when it comes to pricing, marketing, and what your home will actually sell for.
Living in fort collins x The Soukup Group
Expert market analysis and Northern Colorado lifestyle insights from the region's top 1% authority.
Stay ahead of trends
FORT COLLINS AND BEYOND Market UPDATES.
Go beyond the headlines with our deep-dive analysis into local real estate trends and economic shifts. We translate complex market data into actionable advice for homeowners and investors.